What Is the 30-60-10 Investment Strategy?
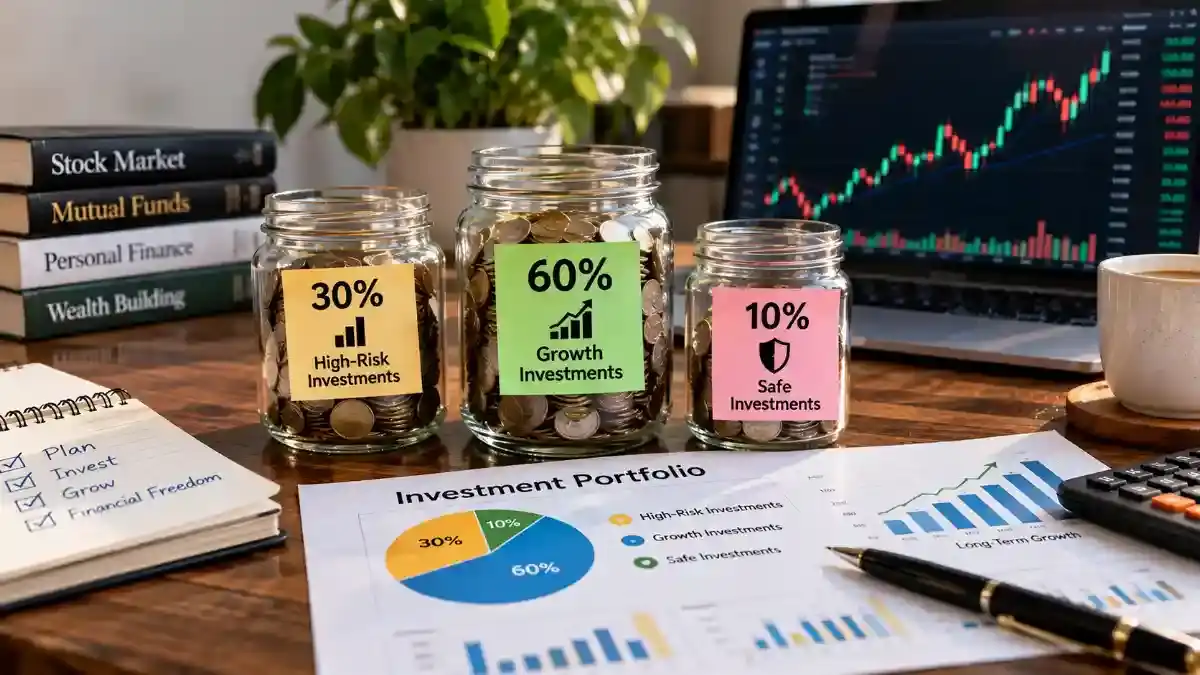
The 30-60-10 rule is a portfolio allocation framework that divides your investable money into three buckets:
| Bucket | Allocation | Purpose |
|---|---|---|
| 60% Core | Stable, diversified assets | Steady growth, capital preservation |
| 30% Growth | Equities / index funds | Long-term wealth building |
| 10% High-Risk | Speculative bets | Asymmetric, outsized returns |
Some investors flip it to 60-30-10 (60% growth, 30% core, 10% speculative), but the philosophy is identical: protect most of your money, grow a meaningful chunk of it, and swing for the fences with a small slice you’re fully prepared to lose.
Quick Fact: The idea is rooted in a concept institutional investors call “barbell strategy” — combining extreme safety with extreme risk while avoiding the mediocre middle.
Breaking Down Each Bucket in Detail
Bucket 1: The 60% Core (Your Safety Engine)
This is the foundation of the portfolio. The goal here isn’t to make you rich overnight — it’s to ensure you never go broke while earning consistent, boring returns.
What belongs in the 60% core:
- Broad-market index funds (S&P 500, Nifty 50, FTSE World)
- High-quality government bonds and treasury funds
- Blue-chip dividend stocks
- Money market funds for liquidity
Expected return: 6–9% annually (historical averages)
Why it matters: Compounding is the single most powerful force in investing. A stable 60% base means your portfolio keeps growing even if your speculative bets go to zero.
Bucket 2: The 30% Growth (Your Wealth Builder)
This bucket is where real long-term wealth gets built. It’s aggressive but not reckless.
What belongs in the 30% growth bucket:
- Individual growth stocks (tech, AI, green energy)
- Sector-specific ETFs
- International/emerging market funds
- Small-cap and mid-cap funds
Expected return: 10–15% annually (with higher volatility)
The logic: While the 60% core keeps you safe, the 30% growth bucket accelerates your journey toward financial goals — retirement, home ownership, financial independence.
Bucket 3: The 10% High-Risk (Your Lottery Tickets)
This is the bucket that makes the 30-60-10 strategy “high-risk” — but it’s also where the magic happens.
What belongs in the 10% speculative bucket:
- Cryptocurrency (Bitcoin, Ethereum, altcoins)
- Individual tech/AI startup stocks
- Options and leveraged positions
- Pre-IPO or private equity opportunities
- Meme stocks or momentum trades
Expected return: -100% to +1,000% (literally anything is possible)
The golden rule: Never put money here that you can’t afford to lose 100% of. This bucket can go to zero, and your portfolio must survive that outcome.
Why the 30-60-10 Strategy Works (The Psychology Behind It)
1. It Controls Emotional Decision-Making
Most investors lose money not because of bad assets, but because of bad behavior — panic selling, FOMO buying, revenge trading. By capping speculation at 10%, the strategy removes emotional damage from the equation.
2. It Captures Asymmetric Upside
A 10% allocation to a speculative asset that 10x’s becomes 100% of your portfolio. Meanwhile, if it goes to zero, you’ve only lost 10%. That’s asymmetry — limited downside, unlimited upside.
3. It Survives Black Swan Events
COVID crash (2020), crypto winter (2022), tariff shocks (2025) — portfolios built on 30-60-10 principles survived all of them because the core 60% never stopped working.
4. It Forces Discipline Through Rebalancing
Every quarter or year, you rebalance back to 30-60-10. This automatically means selling high and buying low — the holy grail of investing, executed mechanically.
Who Should Use the 30-60-10 Strategy?
✅ It’s a good fit if you:
- Are between 20–45 years old with a long investment horizon (10+ years)
- Have a stable income and emergency fund (3–6 months of expenses saved)
- Can emotionally handle seeing 10% of your portfolio drop 50% in a week
- Want exposure to crypto/AI/high-growth assets without betting everything
❌ Avoid this strategy if you:
- Are nearing retirement (consider 60-40 or more conservative splits instead)
- Have less than ₹5 lakh / $10,000 in total investable assets
- Will need this money within 3–5 years
- Lose sleep over market volatility
How to Implement the 30-60-10 Strategy: Step-by-Step
Step 1: Build Your Emergency Fund First
Before touching any investment bucket: 3–6 months of living expenses in a high-yield savings account. Non-negotiable.
Step 2: Define Your 60% Core
Open an account with a low-cost broker and allocate 60% into:
- 40% — Broad market index fund (e.g., S&P 500 ETF)
- 20% — Bond index fund or treasury ladder
Step 3: Build Your 30% Growth Allocation
- 20% — Growth/tech sector ETFs
- 10% — Individual stock picks based on research
Step 4: Allocate Your 10% Speculative Bucket
Choose 2–4 high-conviction speculative positions. Diversify within the bucket. For example:
- 5% — Bitcoin/major cryptocurrencies
- 3% — AI or biotech individual stocks
- 2% — Options or early-stage opportunities
Step 5: Automate and Rebalance
- Set up automatic monthly contributions
- Rebalance every 6–12 months (or when any bucket drifts ±5% from target)
- Use tax-advantaged accounts (401k, IRA, PPF, NPS) wherever possible
Real-World Example: ₹10,00,000 Portfolio
| Bucket | Amount | Example Holdings | 1-Year Scenario (Bull Market) | 1-Year Scenario (Bear Market) |
|---|---|---|---|---|
| 60% Core | ₹6,00,000 | Index funds + bonds | ₹6,48,000 (+8%) | ₹5,70,000 (-5%) |
| 30% Growth | ₹3,00,000 | Growth stocks/ETFs | ₹3,60,000 (+20%) | ₹2,40,000 (-20%) |
| 10% Speculative | ₹1,00,000 | Crypto/high-risk | ₹2,00,000 (+100%) | ₹50,000 (-50%) |
| Total | ₹10,00,000 | — | ₹12,08,000 (+20.8%) | ₹8,60,000 (-14%) |
Notice: even in a bear market, the portfolio only drops ~14% — painful but survivable. In a bull market, the speculative bucket supercharges returns.
Common Mistakes to Avoid with the 30-60-10 Strategy
Mistake 1: Letting the 10% Become 40%
When crypto or a hot stock moons, your speculative bucket grows beyond 10%. Rebalance. Greed is how strategies die.
Mistake 2: Confusing “High-Risk” with “Gambling”
Speculative should mean high-reward potential based on research — not random meme coin pumps. Every position in the 10% bucket should have a thesis.
Mistake 3: Ignoring Fees and Taxes
High-frequency trading in the speculative bucket can eat returns through short-term capital gains taxes and transaction fees. Be mindful.
Mistake 4: Skipping the Emergency Fund
Investing your rent money in a “stable” index fund is still investing money you can’t afford to lock up. Emergency fund first, always.
30-60-10 vs. Other Popular Strategies
| Strategy | Allocation | Risk Level | Best For |
|---|---|---|---|
| 30-60-10 | 60% core / 30% growth / 10% speculative | Medium-High | Young, aggressive investors |
| 60-40 | 60% stocks / 40% bonds | Medium | Balanced, mid-career investors |
| 100% Index | All index funds | Medium | Hands-off, passive investors |
| Core-Satellite | 70-80% core / 20-30% satellites | Medium | Moderate risk-takers |
| All-In Growth | 100% equities | Very High | Very young, high risk tolerance |
The Bottom Line
The 30-60-10 investment strategy isn’t a get-rich-quick scheme — it’s a get-rich-and-stay-rich framework. By protecting 60% of your capital, aggressively growing 30%, and swinging for home runs with 10%, you build a portfolio that:
- ✅ Survives market crashes
- ✅ Compounds steadily over decades
- ✅ Captures life-changing upside from asymmetric bets
- ✅ Keeps your emotions (and mistakes) in check
The key isn’t the numbers — it’s the discipline. The investors who win with this strategy aren’t the ones with the best stock picks. They’re the ones who rebalance, stay patient, and never risk more than they can afford to lose.
Disclaimer: This article is for educational purposes only and does not constitute financial advice. Investing involves risk, including the possible loss of principal. Past performance does not guarantee future results. Always consult a certified financial advisor before making investment decisions, and consider your own risk tolerance, time horizon, and financial situation.
Frequently Asked Questions (FAQs)
Q1. Is the 30-60-10 strategy suitable for beginners?
Yes, if you’re under 40 and have an emergency fund. Its structured nature actually makes it easier for beginners than unstructured investing. Just avoid complex instruments like options in the 10% bucket until you understand them.
Q2. Can I modify the percentages?
Absolutely. The 30-60-10 rule is a template, not gospel. Some investors use 50-40-10 (more conservative) or 60-35-5 (less speculative). Adjust based on your age, goals, and risk tolerance.
Q3. Should I rebalance monthly or yearly?
Yearly is sufficient for most investors, or when allocations drift more than 5% from targets. Frequent rebalancing increases costs and taxes without meaningful benefit.
Q4. What if my speculative 10% goes to zero?
That’s the design working as intended. Your 90% core-and-growth portfolio continues compounding. Refill the 10% bucket only when you’re financially comfortable doing so.
Q5. Does this strategy work in India?
Yes. Use Nifty 50 index funds and debt funds for the core, flexi-cap/growth funds for the middle bucket, and SEBI-regulated crypto exchanges for the speculative bucket (with full awareness of crypto’s regulatory status and 30% flat tax on gains in India).